In Financial Services, Let AI Prepare the File Before It Influences the Decision
The best first AI use case in financial services may not be a new scoring model. It may be the unglamorous work that happens before a person can make a well-supported decision: preparing a complete, organized file.
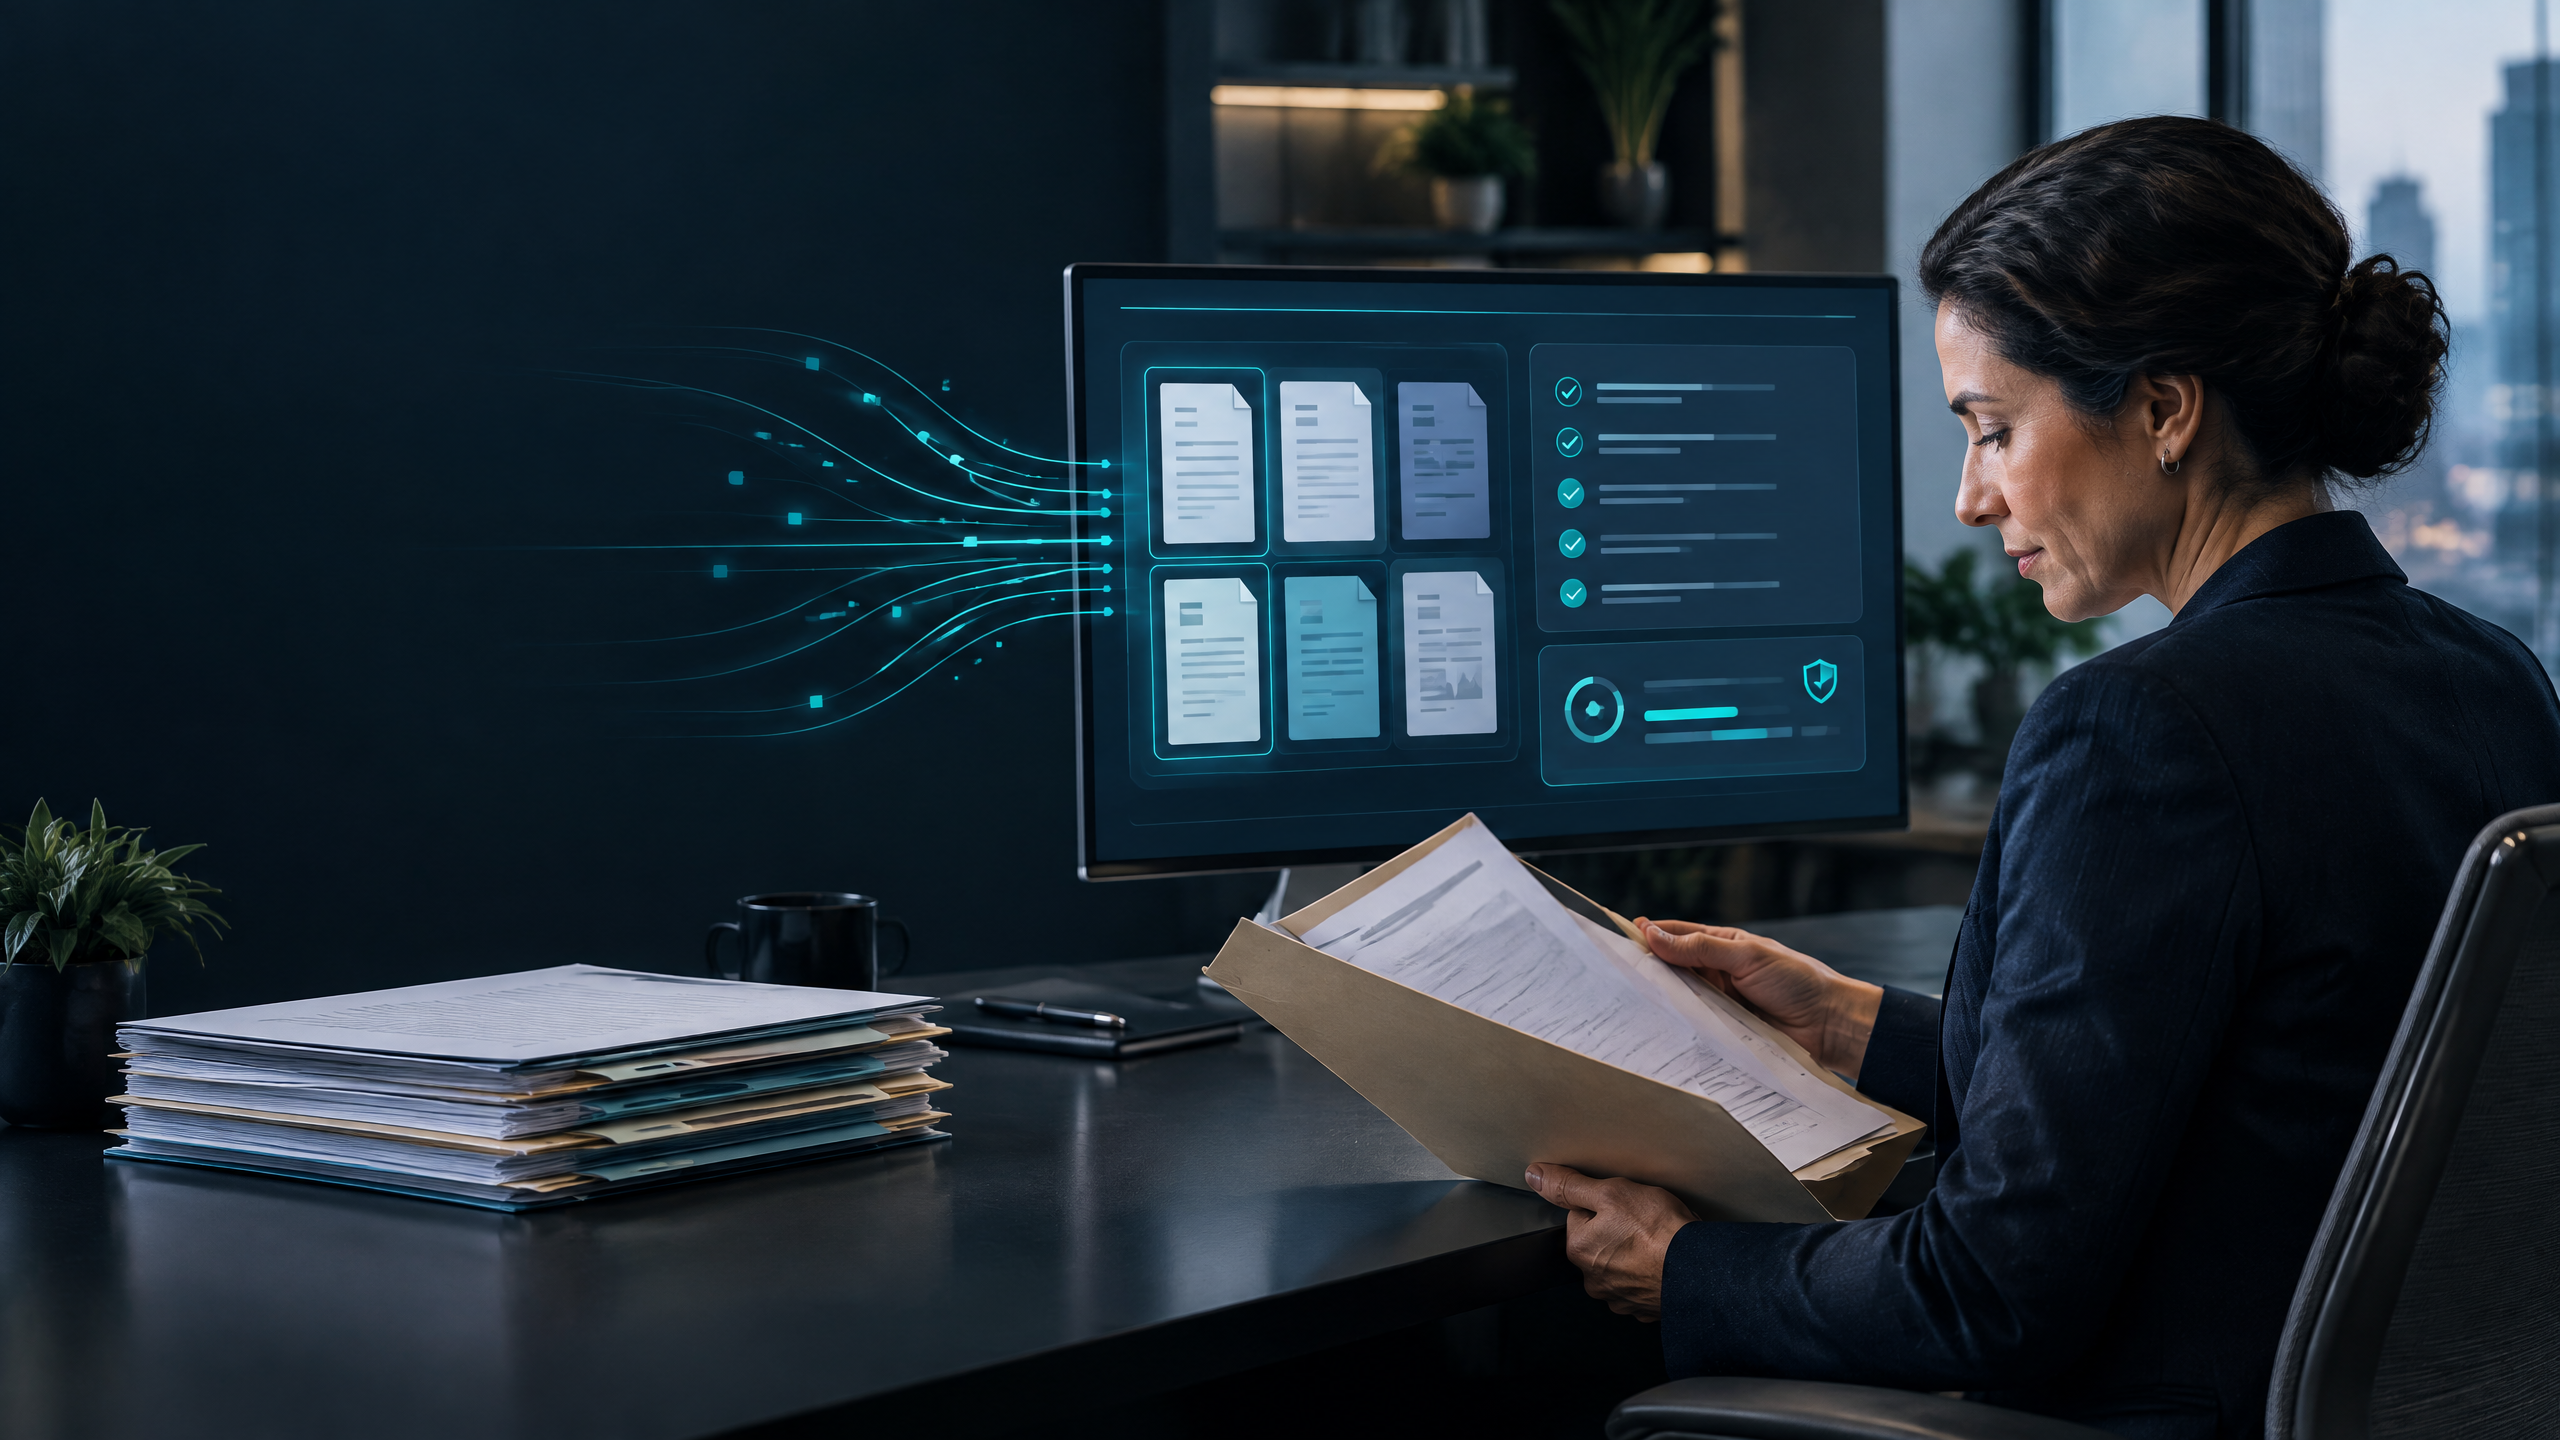
The most useful first AI project in a financial-services operation often has nothing to do with making the decision. It has to do with preparing the file.
Think about a normal morning in an operations team. Applications, statements, identification documents, tax forms, correspondence, and supporting records arrive through email, portals, and shared inboxes. Someone opens each item, identifies what it is, checks whether the file is complete, enters basic information, and sends a follow-up if something is missing. It is necessary work. It is also repetitive, easy to interrupt, and difficult to see as a single process when it is spread across several people and systems.
That is where AI can be useful without becoming the decision-maker.
A well-designed document-intake workflow can classify incoming files, extract agreed fields, compare them against a checklist, identify missing items, and route uncertain cases to the right person. The output is a better-prepared file and a clearer work queue. It is not an automatic credit approval, denial, pricing decision, investment recommendation, or compliance conclusion.
That distinction matters. In financial services, a faster process is only valuable if the organization can still explain what happened, who reviewed it, and what authority the system did or did not have.
Start with the work before the decision
Many organizations begin an AI conversation at the most sensitive point in the process. They ask whether a model can approve an application, estimate risk, or recommend an outcome. Those questions are not off limits, but they are rarely the right first step.
The stronger first question is simpler: where does the team spend time preparing information for someone else to review?
For a lender, that may mean checking whether an application package includes the documents required by the current process. For a bank, it may mean organizing account-opening records and flagging missing information for a trained reviewer. For an advisory, wealth-management, or insurance operation, it may mean sorting client documents, creating a case summary, and making sure the next person sees the relevant information in one place.
Banks operating a Customer Identification Program, for example, need procedures to obtain and verify certain customer information using a risk-based approach. An AI workflow may help organize records and flag incomplete packages, but it does not replace identity-verification procedures or the institution's judgment about an exception.[4]
The operational benefit is straightforward. Instead of using experienced staff to find, rename, and re-enter information, the team can focus on the files that are incomplete, unusual, urgent, or genuinely difficult.
What a sensible workflow looks like
A practical first workflow has five parts.
1. Capture documents only through approved channels. The process should begin in the firm's approved inbox, portal, document-management system, or other controlled environment. Client records should not be copied casually into a general-purpose AI tool. The data boundary, vendor arrangement, access permissions, retention settings, and security review need to be established before the pilot begins.
2. Classify and extract agreed information. The system can identify document types and pull out only the fields the team has agreed are useful for the intake step. The goal is not to extract every word from every page. It is to prepare a useful starting point for the reviewer.
3. Check the package against a defined checklist. AI is most helpful when the process already has a clear standard. For example, the workflow can compare the received documents with a product-specific checklist and flag that an expected item is missing, unreadable, expired, or inconsistent with the file. If the checklist is unclear or changes from person to person, solve that process problem first.
4. Route exceptions to a person. Low-confidence extraction, missing documents, conflicting information, unusual cases, and anything that could affect a customer outcome should move to a designated reviewer. The human should see the source document, the extracted information, the reason for the flag, and the next step. A queue without context simply turns automation into another inbox.
5. Keep a usable record. The organization should be able to see what entered the workflow, what the system extracted, what was flagged, who reviewed it, and how the issue was resolved. This does not need to become an oversized project. It does need to be reliable enough for operations, internal review, and incident follow-up.
This approach follows the practical logic of the NIST AI Risk Management Framework: establish governance, understand the context, measure performance, and manage the risk through the lifecycle. NIST describes the framework as voluntary guidance, not a substitute for sector-specific legal or compliance advice.[2]
Why this is a safer place to begin
Document intake is not risk-free. Errors can still delay a customer, create a privacy issue, or send work to the wrong queue. But it is easier to test, observe, correct, and govern than an AI system that directly changes a customer's access to credit or another consequential service.
That is especially important for lenders. The Consumer Financial Protection Bureau has stated that lenders using AI and other complex models must provide accurate and specific reasons for adverse actions. There is no special exemption because a model is difficult to explain.[3]
A document-preparation workflow does not solve that obligation, and it should not be presented as a way around it. It simply keeps the first implementation away from the point where an automated output could become a customer decision. If a future use case involves underwriting, pricing, eligibility, adverse action, or another regulated determination, involve the appropriate compliance, legal, model-risk, and business owners from the start.
A better 30-day pilot
The first pilot should be narrow enough to learn from. Choose one document stream, one team, one checklist, and one named owner.
Before switching anything on, measure the current process. How long does it take to prepare a file? How often does the team need to request missing information? How many corrections are made after the first review? Where does work sit too long? A baseline matters because a pilot without a baseline produces opinions, not evidence.
Then run the workflow in parallel. Let the system prepare a file, but keep the existing human review and release step. Compare the results. Did it classify documents correctly? Did it flag real gaps? Did it create new exceptions? Did staff find the prepared file useful? Were there access, quality, or process issues that need attention before expansion?
The right result may be a modest one. Perhaps the team finds that the system reliably organizes routine files but needs more training on certain document formats. That is still valuable. It gives the organization a controlled way to improve the workflow before it touches a more sensitive decision.
The U.S. Treasury's Financial Services AI Risk Management Framework was released in 2026 to give financial institutions scalable tools for evaluating AI use cases and managing lifecycle risks, accountability, transparency, and resilience.[1] That is a useful standard for a small pilot as much as for a larger program: know what the tool does, know what it does not do, and name the person responsible for the outcome.
The point is not to remove judgment
The goal is not to make a financial-services process feel automatic. It is to remove low-value friction so skilled people can apply judgment where it matters.
A well-run intake workflow should make the reviewer more effective, not less accountable. It should give the customer fewer unnecessary follow-ups, give the operations team a clearer queue, and give management a more visible process. If it cannot do those things with appropriate controls, it is not ready to expand.
Financial services does not need to begin its AI journey with the hardest decision in the business. It can begin with the work that makes a good decision possible: a complete file, a clear exception, and a qualified person who understands the context.
This article offers operational guidance only. It is not legal, regulatory, or compliance advice. Organizations should involve qualified counsel and compliance professionals for use cases that may affect consumer rights, account opening, credit, pricing, eligibility, or other regulated decisions.
Sources Reviewed
These sources were reviewed for the article’s regulatory and governance context. They are not a substitute for advice on a specific use case.
Have a question about this article?
Chat with our team directly on WhatsApp.
Pedro Prado
Founder, Prado AI Solutions. 30+ years in operational risk, audit, and controls. Published author on AI. Trilingual: English, Spanish, Portuguese.